Pet insurance for dogs can be worth the cost when an unexpected veterinary bill would otherwise force you to use high-interest debt, delay treatment, or choose a less effective treatment solely because of price. It is less compelling when you already have enough accessible savings to handle major veterinary expenses and are comfortable accepting that financial risk yourself.
Insurance does not make veterinary care free, and it will not cover every condition. You will normally pay premiums, meet a deductible, cover your share of eligible expenses, and pay entirely for excluded care. The real question is therefore not, “Will I get back more than I pay every year?” It is, “How much financial risk can I safely carry if my dog becomes seriously ill or injured?”
Understanding the costs, limitations, reimbursement process, and alternatives can help you make that decision without treating insurance as either a guaranteed bargain or a waste of money.
Table of Contents
Is Pet Insurance for Dogs Worth It?
For many owners, pet insurance for dogs is worthwhile as protection against an unpredictable, financially disruptive veterinary bill. However, its value depends on your finances, your dog’s age and medical history, and the exact policy.
Insurance may be especially valuable when:
- You could afford a monthly premium but not a sudden bill of several thousand dollars.
- You want access to emergency care, surgery, hospitalization, or specialist treatment without relying entirely on credit.
- Your dog is still young and has few or no documented medical problems.
- You own a breed with elevated risk of certain covered hereditary conditions.
- You would find it emotionally difficult to place a strict dollar limit on emergency treatment.
- You prefer predictable monthly expenses over an unpredictable financial loss.
It may be less valuable when:
- You have a large, dedicated, immediately accessible veterinary emergency fund.
- Your dog already has several conditions that a new insurer would classify as pre-existing.
- The available plans exclude the conditions you are most concerned about.
- Premiums for your older dog are unaffordable or would undermine other essential expenses.
- The policy has a low annual limit, restrictive reimbursement rules, or exclusions that substantially reduce its usefulness.
The American Veterinary Medical Association’s consumer guidance emphasizes that there is no single formula that determines whether insurance is right for every owner. Researching policies and discussing your dog’s health risks with your veterinarian are both sensible steps.
Pet insurance should be viewed primarily as risk protection—not an investment that is expected to generate a profit.
How Does Pet Insurance for Dogs Work?
Most dog insurance policies operate differently from human health insurance. You can generally visit a licensed veterinarian of your choice, pay the bill, and then submit a claim for reimbursement. Some insurers have direct-payment arrangements, but owners should not assume that option is available at every veterinary hospital.
A typical policy includes five important components.
Premium
The premium is the monthly or annual amount you pay to keep the policy active. You continue paying it whether or not you submit a claim.
Deductible
The deductible is the amount of eligible veterinary expense you must absorb before reimbursement begins. A policy may use:
- An annual deductible that resets each policy year
- A per-condition deductible
- A per-incident deductible
An annual deductible is usually easier to evaluate because you know the maximum deductible that will apply during that policy year. Per-condition deductibles may work differently for chronic conditions, so read the policy language carefully.
Reimbursement rate
After the applicable deductible, the insurer reimburses a specified percentage of covered expenses. Common options include 70%, 80%, and 90%.
A 90% reimbursement rate does not necessarily mean the insurer pays 90% of the entire invoice. Excluded services, the deductible, and expenses above the annual limit can remain your responsibility.
Annual or lifetime limit
This is the most the insurer will reimburse during a defined period. Some plans have annual limits such as $5,000 or $10,000, while others advertise unlimited annual benefits.
A lower limit can reduce the premium, but it may provide inadequate protection during cancer treatment, major surgery, or a year involving several unrelated illnesses.
Waiting period
Coverage generally does not begin immediately. Accident and illness waiting periods may differ, and some orthopedic conditions can have longer waiting periods.
A condition that begins or shows signs during the waiting period may be excluded as pre-existing. Buying a policy after a diagnosis or accident will not make that existing problem covered.
How Much Does Dog Insurance Cost?
Premiums vary substantially, so national averages should be treated as reference points rather than quotes for a particular dog.
The latest public North American Pet Health Insurance Association industry data reports continued growth in the North American insurance market. Data for 2024 cited from NAPHIA’s industry reporting placed the average US accident-and-illness premium for dogs at approximately $749 per year, or about $62 per month.
Actual quotes can fall below or substantially above that average. Insurers commonly consider:
- Dog’s age
- Breed
- ZIP code and local veterinary costs
- Accident-only versus accident-and-illness coverage
- Annual benefit limit
- Deductible
- Reimbursement percentage
- Optional wellness benefits
- Insurer pricing and underwriting rules
A young mixed-breed dog in an area with lower veterinary prices may receive a comparatively inexpensive quote. An older purebred dog in a high-cost city may cost considerably more to insure.
Premiums may also rise at renewal. A low starting quote does not guarantee a low lifetime cost, which is why owners should examine available policy documents and ask how age-related pricing works.
Pet insurance is only one part of the overall expense of dog ownership. PawMindTips’ guide to dog care costs can help you account for food, routine veterinary care, grooming, supplies, training, and other recurring expenses alongside insurance premiums.
What Does Pet Insurance for Dogs Cover?
Coverage depends on the plan rather than the company’s advertising headline. The three common coverage categories are accident-only, accident-and-illness, and wellness care.
Accident-only coverage
Accident-only plans may cover eligible treatment resulting from events such as:
- Broken bones
- Bite wounds
- Cuts and lacerations
- Vehicle-related injuries
- Some toxin exposures
- Swallowed foreign objects
- Burns or traumatic injuries
This may be an affordable option for catastrophic accident protection, but it will not normally cover infections, cancer, allergies, arthritis, or other illnesses.
Accidental poisoning is one reason emergency expenses can appear without warning. Reducing access to household items poisonous to dogs remains important even when insurance is in place.
Accident-and-illness coverage
This is broader coverage and typically includes eligible accidents plus newly developed illnesses. Depending on the policy, benefits may include:
- Diagnostic tests
- Surgery
- Hospitalization
- Prescription medication
- Cancer treatment
- Emergency care
- Specialist care
- Hereditary or congenital conditions
- Chronic-condition management
Do not assume every item related to a covered condition is reimbursable. Examination fees, rehabilitation, behavioral therapy, dental illness, prescription diets, complementary care, and take-home medication may be included by one policy and excluded by another.
Wellness or preventive-care benefits
Wellness packages may help pay for scheduled services such as:
- Physical examinations
- Vaccinations
- Heartworm testing
- Parasite prevention
- Routine bloodwork
- Spaying or neutering
- Dental cleaning
These packages are often add-ons rather than traditional insurance against unpredictable loss. Compare the annual price of the package with its reimbursement schedule. If its maximum benefits roughly equal its additional premiums, it may function more like a budgeting program than insurance.
What Does Dog Insurance Usually Exclude?
Exclusions are where superficially similar policies can become very different.
Pre-existing conditions
Most policies exclude conditions that existed, were diagnosed, or showed clinical signs before coverage began or during a waiting period. The exclusion may apply even when the final diagnosis was made later.
For example, if the veterinary record documents recurring limping before enrollment, a later orthopedic diagnosis could be considered related to a pre-existing problem.
Some insurers distinguish between curable and incurable pre-existing conditions and may reconsider certain curable problems after a symptom-free interval. This is entirely policy-dependent.
Other common exclusions or limitations
Depending on the policy, exclusions may include:
- Elective and cosmetic procedures
- Breeding, pregnancy, and delivery
- Routine or preventive care without a wellness benefit
- Grooming and boarding
- Prescription food
- Experimental treatment
- Certain dental conditions
- Behavioral treatment
- Organ transplants
- Non-veterinary expenses
- Conditions specifically excluded by endorsement
Breeding exclusions deserve particular attention because reproductive emergencies can be expensive. Owners involved in breeding should not assume a standard plan will reimburse treatment for dystocia in dogs or a related cesarean delivery.
Read the sample policy, definitions, exclusions, and endorsements—not only the benefits summary. If wording is unclear, ask the insurer to explain it in writing before buying.
Pros and Cons of Pet Insurance for Dogs
| Potential advantages | Potential disadvantages |
|---|---|
| Reduces exposure to large covered veterinary bills | Premiums continue even in years with no claims |
| May make specialist or emergency treatment more financially accessible | Most policies exclude pre-existing conditions |
| Converts part of an unpredictable risk into a regular expense | Owners may have to pay the veterinarian upfront |
| Usually permits use of any licensed veterinarian | Deductibles, copayments, limits, and exclusions still apply |
| Can be especially useful when purchased before health problems appear | Premiums can increase as the dog ages |
| Provides emotional reassurance during medical decisions | Claims can be denied when treatment is not covered |
| May cover chronic or hereditary conditions when included by the policy | Routine care usually requires a separate benefit |
The strongest argument for pet insurance for dogs is not that it saves every policyholder money. Insurance pools risk: many owners pay premiums so that covered owners facing major losses can receive reimbursement.
The strongest argument against it is that the owner may pay premiums for years while receiving little or no reimbursement. That outcome does not mean the policy failed, however. The owner purchased financial protection during that period, just as someone can buy home insurance without experiencing a house fire.
The decision turns on whether the protection is appropriately priced for the financial risk you want to transfer.
A Realistic Pet Insurance Claim Example
Claim calculations reveal more than a premium alone.
Suppose your dog receives a $6,000 emergency veterinary bill. Your plan has:
- A $500 annual deductible
- An 80% reimbursement rate
- A $10,000 annual benefit limit
Assume the entire bill is eligible and no deductible has been paid that year.
- Eligible bill: $6,000
- Minus deductible: $5,500
- Insurer reimburses 80% of $5,500: $4,400
- Your share after reimbursement: $1,600
You may initially need to pay the full $6,000 unless the insurer and hospital support direct payment.
Now assume that $600 of the bill consists of excluded examination fees or other non-covered services:
- Covered portion: $5,400
- Minus deductible: $4,900
- Reimbursement at 80%: $3,920
- Your final responsibility: $2,080
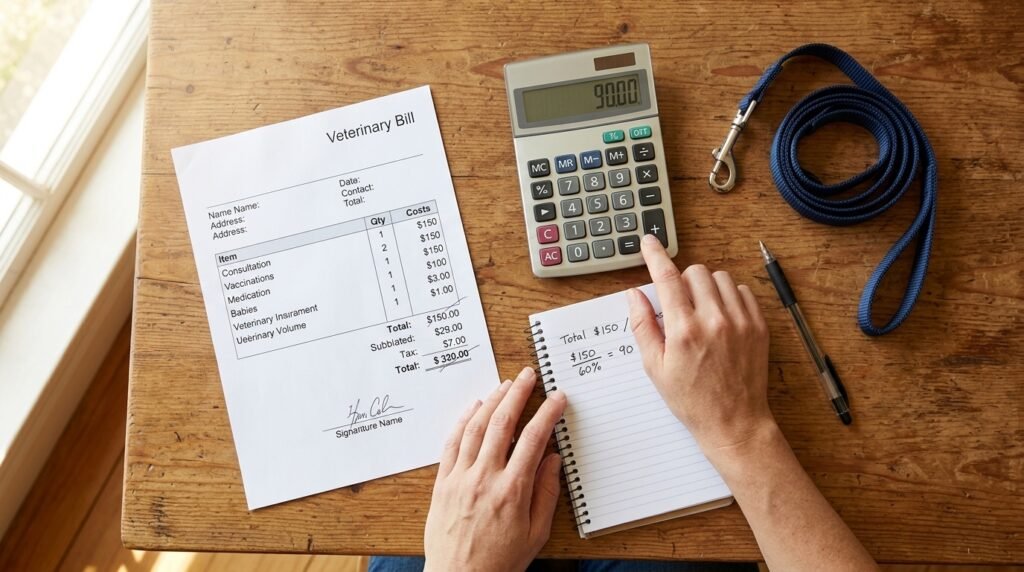
That difference illustrates why “80% reimbursement” is not the same as receiving 80% of every invoice.
Before enrolling, ask how the insurer applies the deductible and reimbursement rate. Some plans subtract the deductible first; other calculations or benefit schedules can produce a different result.
When Is Pet Insurance Most Likely to Be Worth It?
For puppies and young dogs
This is often the most favorable enrollment period. Premiums are usually lower, and young dogs are less likely to have accumulated pre-existing conditions.
Puppies are not risk-free. They may swallow objects, ingest toxins, suffer injuries, or develop congenital or hereditary problems. Enrolling early can protect against future eligible conditions, but it will not cover problems that already appeared before enrollment.
When you cannot comfortably absorb a major bill
If a $5,000 veterinary expense would require high-interest credit, borrowing from retirement savings, or delaying essential household expenses, insurance may offer meaningful protection.
Even with coverage, you need enough cash or available credit to pay your deductible, coinsurance, excluded services, and possibly the entire bill while waiting for reimbursement.
For breeds with known health risks
Breed risk can make insurance more valuable, but only when the relevant conditions are actually covered. Look specifically for policy language concerning:
- Hereditary conditions
- Congenital conditions
- Hip dysplasia
- Cruciate ligament problems
- Brachycephalic disorders
- Breed-specific exclusions
- Bilateral-condition exclusions
Never assume “illness coverage” automatically includes every inherited disorder.
When you want broader treatment choices
Coverage may make it easier to consider specialist consultation, advanced diagnostics, surgery, hospitalization, or ongoing treatment. It does not guarantee that every option will be reimbursed, but a strong policy can reduce the role immediate cost plays in medical decisions.
The AVMA’s policy on pet health insurance supports owners retaining the ability to choose their veterinarians, including specialists and emergency facilities.
When Might Pet Insurance Not Be Worth It?
A new policy may offer limited value when a senior dog already has multiple chronic conditions that will be excluded. The policy could still cover unrelated future accidents or illnesses, but you must decide whether that remaining protection justifies the premium.
Self-funding may also be reasonable if you have enough dedicated savings to pay for a major veterinary emergency immediately. “Enough” should reflect realistic emergency and specialist expenses, not merely the cost of a routine appointment.
Insurance may be a poor choice when:
- Premiums prevent you from paying for food, preventive care, or necessary medication.
- The annual limit is too low to protect against the bills that concern you.
- The policy excludes major breed-related risks.
- You do not have a way to pay the veterinarian while awaiting reimbursement.
- You have not read the exclusions and are buying based on marketing language alone.
Canceling an existing policy requires particular care. Conditions diagnosed under the old insurer will normally be treated as pre-existing by a new company. Switching can also introduce new waiting periods.
Pet Insurance Versus an Emergency Savings Fund
An emergency fund gives you complete control over the money. There are no claim forms, denials, reimbursement percentages, or coverage restrictions. Unused money remains yours.
Its major weakness is time. Saving $75 per month produces $900 after one year and $4,500 after five years, before interest. A serious emergency could happen during the first month.
Insurance can provide access to a much larger covered benefit soon after applicable waiting periods end, but premiums are not returned simply because you submit no claims.
For many households, the strongest approach is a combination:
- Carry accident-and-illness coverage for major eligible expenses.
- Maintain savings for the deductible and coinsurance.
- Keep additional funds for excluded services and routine care.
- Have a payment plan for the period before reimbursement arrives.
The Insurance Information Institute’s pet ownership and insurance statistics demonstrate that veterinary expenses are only one component of the total cost of owning a dog. Do not spend so much on premiums that you can no longer manage predictable daily care.
How to Compare Pet Insurance Policies
Obtain quotes using the same deductible, reimbursement percentage, and annual limit. Comparing a low-limit 70% plan with an unlimited 90% plan based only on premium is misleading.
Use this checklist for each policy:
- Coverage type: Is it accident-only or accident-and-illness?
- Pre-existing-condition definition: Does it include signs documented before diagnosis?
- Waiting periods: When do accident, illness, and orthopedic benefits begin?
- Deductible: Is it annual, per incident, or per condition?
- Reimbursement: Is reimbursement based on the actual invoice or a benefit schedule?
- Annual limit: Is it adequate for serious illness or surgery?
- Examination fees: Are consultation and emergency examination charges covered?
- Hereditary conditions: Are breed-related and congenital conditions included?
- Prescription medication: Are take-home drugs covered?
- Dental care: Does the plan cover dental injury, dental illness, both, or neither?
- Rehabilitation: Are physical therapy and rehabilitation covered?
- Claims process: What records are required, and how are claims submitted?
- Direct payment: Can the insurer pay participating hospitals directly?
- Renewal pricing: Can premiums rise because of age, location, or veterinary inflation?
- Cancellation rules: Can coverage be changed or discontinued at renewal?
- Customer complaints: Is the insurer licensed and in good standing in your state?
Pet insurance is regulated at the state level. The National Association of Insurance Commissioners’ state insurance department directory can help you locate the appropriate regulator, verify licensing, or learn where to submit a complaint.
Ask each company for a sample policy for your state. Save the version you reviewed, along with written answers to important coverage questions.
Frequently Asked Questions
Is pet insurance for dogs worth it for routine veterinary visits?
Usually not by itself. Traditional insurance is primarily intended for eligible accidents and illnesses. Routine examinations, vaccinations, parasite prevention, and dental cleaning generally require a wellness add-on. Compare the add-on’s annual cost with its exact benefit schedule before purchasing it.
Is pet insurance worth it for an older dog?
It can be, but premiums and exclusions are often greater. Review which existing problems will be excluded and whether the policy still provides valuable protection for unrelated future illnesses or accidents. Do not evaluate the premium without examining the remaining eligible coverage.
Can I get dog insurance after a diagnosis?
You may be able to buy a policy, but the diagnosed condition and related signs will generally be treated as pre-existing and excluded. The policy may still cover unrelated conditions that begin after enrollment and the applicable waiting periods.
What deductible and reimbursement rate should I choose?
Choose a deductible you could pay immediately and a reimbursement rate that leaves an affordable share of a major bill. Higher deductibles and lower reimbursement rates usually reduce premiums, but they increase the amount you must pay when treatment is needed.
Conclusion
Pet insurance for dogs is most valuable when it protects your household from a veterinary bill you could not comfortably manage alone. It is not a guarantee that you will recover more money than you pay in premiums, and it cannot replace preventive care or an emergency fund.
Before enrolling, compare equivalent quotes, read the complete policy, calculate a sample claim, and examine exclusions for pre-existing, hereditary, dental, and breed-related conditions. If you buy coverage, keep enough accessible money for the deductible, your coinsurance, excluded expenses, and any upfront payment.
The best decision is the one that gives your dog a realistic path to necessary veterinary care without putting your household’s essential finances at risk.